QUICK ANSWER:
A money lender application in Singapore usually involves submitting your personal and income documents, undergoing an affordability assessment, and attending an in-person verification appointment before the loan can be granted. During the appointment, the licensed moneylender must verify your identity, explain the loan terms in a language you understand, and provide the completed loan contract before disbursement. Attending verification does not mean you are required to proceed with the loan.
✦ KEY TAKEAWAYS
• The in-person meeting is not optional. A licensed moneylender must meet you physically at its approved place of business before granting you a loan. Any lender offering to complete the entire process remotely is not following the rules.
• Verification is about affordability, not just identity. Alongside confirming who you are, the lender considers your income and existing financial commitments, as well as your borrowing and repayment record through the Moneylenders Credit Bureau (MLCB), when assessing the loan.
• Attending the appointment does not commit you to the loan. You do not enter into the loan contract simply by attending verification. The Note of Contract must be signed, and the lender must explain its terms to you in a language you understand before you sign.
• A licensed lender should not ask you to transfer money before disbursement. You should not be asked to make a separate payment, deposit or transfer for “processing” or similar fees before receiving the loan. A loan approval fee of up to 10% of the principal may be charged, but this is deducted from the loan when it is disbursed.
You have compared a few lenders, submitted an online application, and received a message asking you to come in for a verification appointment. Then the questions start. What actually happens at that meeting? What should you bring? And are you already committed to something you have not fully read?
For first-time borrowers, moneylender verification in Singapore may feel unfamiliar. Applying online feels familiar. Signing a contract feels final. The step in between — the in-person verification appointment — is where the lender must confirm your identity and explain the loan terms before approval.
This guide walks through the process as it typically unfolds in Singapore, from application through to disbursement, so you can prepare properly and recognise whether the process you experience is consistent with the requirements for licensed moneylenders.
The word gets used in two different directions, and it is worth separating them before going further.
Verifying the lender means checking that the company you are dealing with actually holds a moneylending license, using the Ministry of Law’s public registry. That is a check you perform before you share any documents.
Borrower verification is the process the lender uses to confirm your identity, assess your income and existing commitments, and determine what it can responsibly lend.
Both matter, and the safer sequence is to verify the lender first. Confirm that the lender is licensed and that its website and address match the official Registry before submitting your documents.
The exact application process can vary between licensed moneylenders, but several rules apply regardless of how a lender structures its process.
You first submit a loan application along with the supporting information the lender requires, such as identification and proof of income. Some lenders may allow parts of this process to be completed digitally, including through services such as MyInfo.
A licensed lender cannot approve a loan before receiving your application form and supporting documents. Approving a loan over the phone, by SMS or by email before those documents have been received is listed by the Ministry of Law as an unacceptable practice — even where the lender is licensed.
The lender assesses the application before deciding whether to offer a loan and, if so, how much.
As part of this process, licensed moneylenders use the Moneylenders Credit Bureau (MLCB), which records borrowing activity involving licensed moneylenders. This helps lenders assess an applicant's existing borrowing and repayment history within the licensed moneylending sector.
There are also legal limits on the total amount of unsecured borrowing a person may have across all licensed moneylenders at any one time. Under Ministry of Law rules, the total maximum amount you may borrow is capped according to your annual income and residency status:
This is a ceiling, not an entitlement. The amount a lender actually offers may be lower, depending on your repayment capacity and existing commitments.
Before you sign the loan contract, the licensed moneylender must explain the loan terms to you in a language you understand. This includes key details such as the loan amount, interest rate, applicable fees, repayment schedule and other relevant terms.
Do not treat any preliminary or indicative information provided earlier in the process as final approval. A licensed moneylender must still complete the required checks before granting the loan.
Before approving a loan, a licensed moneylender must meet the applicant physically at its approved place of business. During this meeting, the lender must verify the applicant's identity against the original identification document and explain the loan's terms and conditions in a language the applicant understands.
This face-to-face step is mandatory. Otherwise, the licensed moneylender cannot complete the entire loan approval and granting process.
If the loan is approved, the loan agreement is completed and the loan is disbursed. A licensed moneylender may deduct a loan approval fee of up to 10% of the principal amount when the loan is granted. The remaining principal must be disbursed without unauthorised deductions.
No other upfront deduction from the principal is permitted, and you should not be asked to make a separate payment before disbursement.
After disbursement, keep records of your repayments. Licensed moneylenders must provide a receipt whenever you make a repayment and a statement of account at least once every January and July for an outstanding loan. These documents help you keep track of how much you have paid and what remains outstanding.
Requirements vary by lender and by your employment situation, so confirm the specific list with your lender beforehand. The table below covers what is commonly requested.
If your income is irregular — for example, if you are commission-based, freelance or self-employed — the lender may ask for different or additional documents to verify your income and repayment capacity. The exact requirements will depend on the lender and your circumstances.
A note on what should never be asked for: a licensed moneylender must not ask for your SingPass user ID or password, must not retain your NRIC or other personal identity documents, and must not ask you to sign a blank or incomplete Note of Contract. These practices are listed by the Ministry of Law as unacceptable, regardless of whether the lender holds a license.
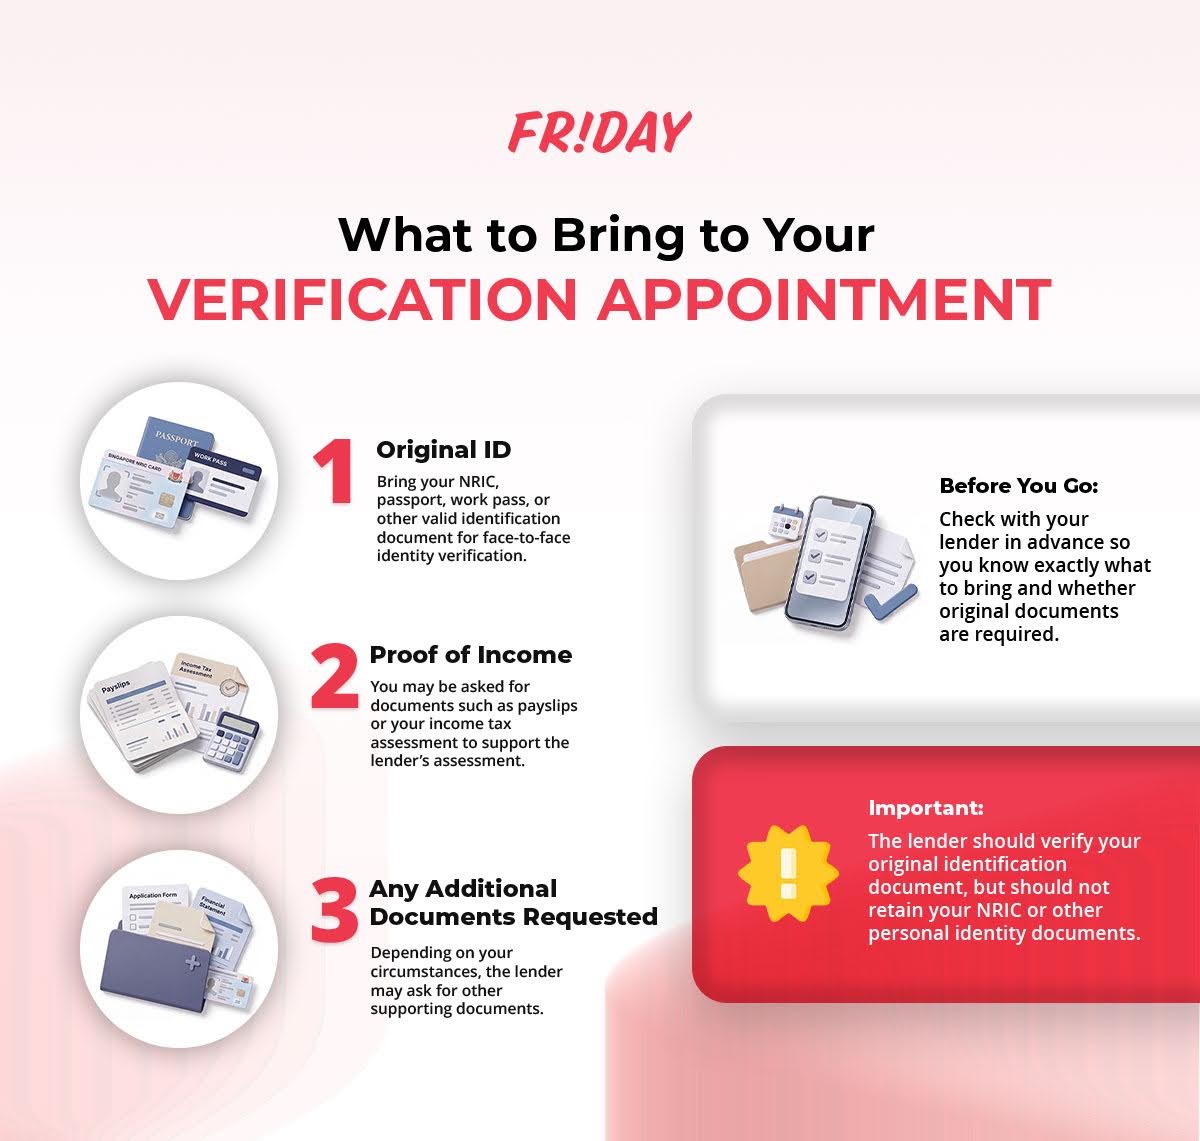
1. Original ID
Bring your NRIC, passport, work pass, or other valid identification document for face-to-face identity verification.
2. Proof of Income
You may be asked for documents such as payslips or your income tax assessment to support the lender’s assessment.
3. Any Additional Documents Requested
Depending on your circumstances, the lender may ask for other supporting documents.
Before You Go
Check with your lender in advance so you know exactly what to bring and whether original documents are required.
Important:
The lender should verify your original identification document, but should not retain your NRIC or other personal identity documents.
For a first-time borrower, this may be the least familiar part of the process. Here is what a properly conducted appointment involves.
Identity confirmation. The lender checks your original identification against the details in your application. Your NRIC may be inspected and returned to you. It must not be kept.
The loan contract is explained. The law requires the lender to explain the terms of the loan to you in a language you understand. This covers the repayment schedule, the interest rate and the applicable fees. If any part is unclear, ask. An explanation you did not follow is not an explanation.
You review the key figures. Interest on a loan from a licensed moneylender is capped at 4% per month, calculated on the principal remaining after payments already made — not on the original amount throughout. Late interest is also capped at 4% per month and can be charged only on an instalment that is actually overdue, not on the remaining balance that is not yet due. Late fees are capped at S$60 per month, and the approval fee at 10% of the principal.
There is also an overall ceiling: the total of interest, late interest, the approval fee and late fees on a loan cannot exceed an amount equal to the principal itself.
You sign the Note of Contract — or you do not. Before signing, make sure the Note of Contract is properly completed and that you understand its terms. MinLaw advises borrowers not to rush into committing to a loan until they are satisfied with the terms and conditions. You should not sign a blank or incomplete Note of Contract.
You receive your copy. The lender must provide you with a copy of the loan contract. Keep it.
Timelines vary considerably and can depend on factors such as how complete your documents are, your circumstances, and the lender’s assessment process. As a general guide:
Incomplete or inconsistent documentation can delay the assessment, particularly if the lender needs to clarify information or request additional documents. Providing the required information accurately and completely can help avoid unnecessary back-and-forth.
Be cautious of any lender suggesting that the entire loan process can be completed remotely without an in-person meeting. Licensed moneylenders must meet borrowers in person at their approved place of business for face-to-face identity verification before granting a loan. Licensed moneylenders are also not permitted to solicit loans through phone calls or text messages, so an unsolicited loan offer through these channels should not be treated as a normal licensed-lending approach.
Verification is not only the lender assessing you. It is also your opportunity to assess the arrangement. Before signing, work through the following:
Questions worth asking directly: What is the total amount I will repay? What is the earliest I can settle this, and does that reduce the interest? What happens if my circumstances change mid-tenure?
The verification process exists for good reasons, but it is worth being clear about both sides.
What it does well. The in-person requirement adds a face-to-face identity check that cannot be completed through a fully remote process. The affordability assessment, including the MLCB check, helps lenders assess existing borrowing and repayment records and helps prevent borrowers from borrowing beyond their means. The requirement that terms be explained in a language you understand puts a genuine obligation on the lender, not just a disclosure in fine print.
What it does not do. Verification does not mean the loan is suitable for you. A lender can conduct a fully compliant process and still offer you a loan that strains your budget. The regulatory caps limit what you can be charged; they do not determine whether borrowing is the right decision in your situation.
It also takes time and effort. Gathering documents and attending an appointment is less convenient than an entirely online process, but these steps form part of the checks and safeguards required before a licensed money lender can grant a loan.
The limitation worth sitting with. Borrowing is a commitment that outlasts the relief of receiving the funds. Before you reach the verification stage, consider whether alternatives apply to your situation — including the financial assistance schemes offered by various Government agencies, which the Ministry of Law itself recommends considering before approaching a moneylender.
IFS Consumer Services Private Limited ("IFSCS") is a licensed moneylender operating under the Friday Finance brand name. The current Registry of Moneylenders lists IFSCS under license No. 85/2026.
Friday Finance’s published application process includes submitting an application and loan details, receiving an offer, and attending a loan interview. As a licensed moneylender, IFSCS must also complete the required due diligence, in-person identity verification and explanation of the loan terms before granting a loan.
The point of setting out the process in this level of detail is not to distinguish one lender from another. It is to help borrowers understand the requirements that apply to licensed moneylending, so they are better placed to recognise when something does not match the expected process.
Verification can feel like an obstacle between you and the funds you need. It is more useful to see it as the stage where the arrangement becomes properly visible — where the figures are explained, the terms are set out, and you have the opportunity to ask questions before committing to anything.
Arrive with your documents in order, read the contract carefully, and do not rush into signing until you understand and are satisfied with the terms. If you feel pressured to sign before your questions have been answered, stop and clarify them before proceeding.
IFS Consumer Services Private Limited ("IFSCS") is a licensed moneylender operating under the Friday Finance brand name with License No. 85/2026. This article is provided for general information only and does not constitute financial advice. Loan approval, amounts and terms are subject to assessment and can vary based on individual circumstances. Please consider your financial situation carefully before borrowing.
All regulatory figures in this article were verified against the Ministry of Law’s published guidance on 17 August 2026.

